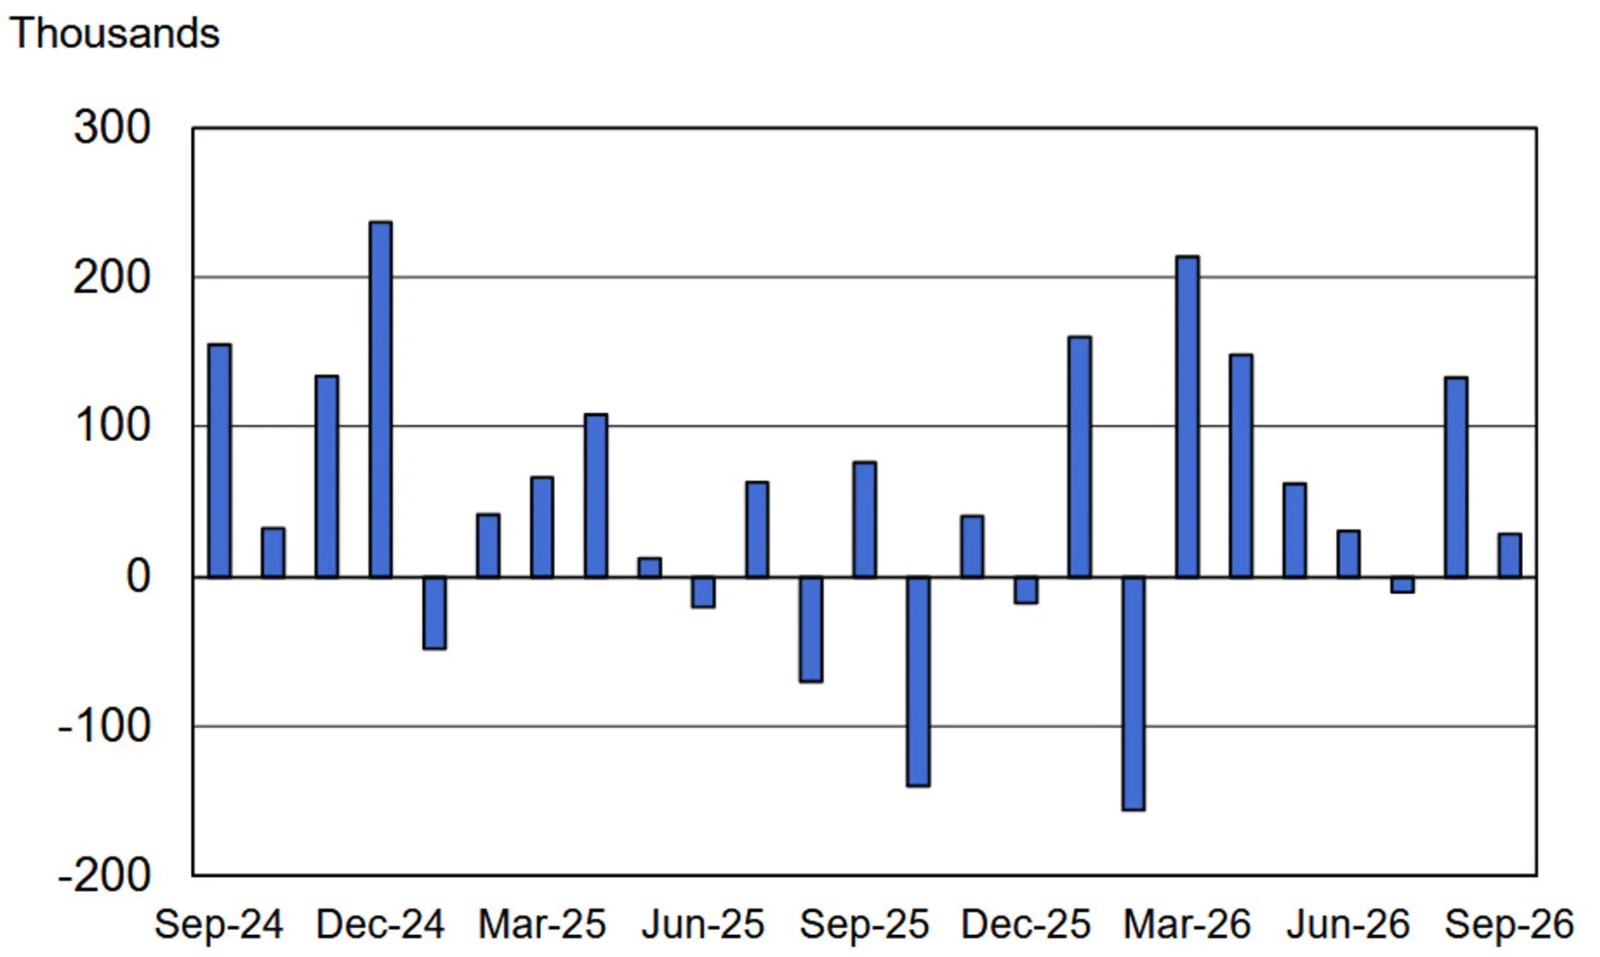
USD: NFP collapses to just 29K, Fed shuts the door on an October hike
10/3/2026
Non-farm payrolls (headline)
Actual: +29K
Consensus: +90K
Previous: +162K (revised to +133K)
Revisions
Two-month net revision: -60K
July now revised to -10K (contraction)
Unemployment rate
Actual: 4.2%
Consensus: 4.1%
Previous: 4.1%
Unrounded: 4.1753% (versus 4.1413% prior), only narrowly above the 4.2% rounding threshold
Average hourly earnings m/m
Actual: +0.1%
Consensus: +0.3%
A sharp gap, the softest monthly gain in this series
Average hourly earnings y/y
Actual: 3.0%
Consensus: 3.2%
Previous: 3.2%
Average weekly hours
Actual: 34.4
Consensus: 34.3
Stable, no sign of aggressive hour-cutting
Private payrolls
Actual: +46K
Consensus: +85K
Previous: +127K
Government payrolls
Actual: -17K
Previous: +35K
The real signal, a weak report across nearly every dimension
Button calls it explicitly "a soft report almost across the board," the headline misses badly, the unemployment rate ticks up, and wage growth comes in much softer than expected
This release directly contradicts the entire hawkish sequence documented this week in this series (ADP +90K, core PCE 3.0%, GDP revised to 2.2%, stable claims, ISM Prices at 77.9%), a sharp reversal after days of data pointing the other way
Immediate market reaction, a massive dovish repricing
October Fed hike odds: 28% before the data, 15% immediately after
USD/JPY: 157.60 before, 157.15 after
US 2-year yield: 4.78% before, 4.72% after
US 10-year yield: 5.23% before, 5.17% after
December now in question, just 88% odds of any hike this year
The key point, wages are the real signal for the Fed
Button stresses wage figures are arguably the most important part for the Fed, and they're clearly soft
+0.1% m/m (5 cents) and a slowdown to 3.0% y/y move in the right direction for the disinflationary path Waller had been arguing for across several weeks in this series
This print directly closes the debate on an October hike, barring an extremely hot CPI in the meantime
The counterweight, the household survey softens the negative read
Employment (household survey): +406K
Labor force: +485K
Participation rate: 61.8% (+0.2pt)
Button explains this is why the rise in unemployment to 4.2% shouldn't be read as particularly ugly, it mostly reflects more people entering the labor force, not mass layoffs
Consistency and break with this series' narrative
This report sharply breaks the hawkish momentum built across four consecutive releases (ADP, PCE, GDP, ISM) documented in the prior analysis in this series
The caution point already flagged before this release, "the surprise risk now sits more on the disappointment side," plays out dramatically here
Implications
DXY: bearish reversal confirmed, the market now prices a Fed on hold, a complete reversal from this week's narrative, consistent with the immediate pullback in USD/JPY and yields noted in the article
EUR/USD, GBP/USD: likely rebound, the Fed conviction gap that had widened all week sharply closes
The upcoming CPI becomes the final arbiter explicitly identified by Button, a very hot print would now be the only scenario capable of reviving the October debate
Point of caution
A single report shouldn't be overinterpreted in either direction, but this one is particularly dense with consistent signals (headline, wages, revisions, unemployment) all pointing to weakness, unlike the scattered releases of prior weeks
The gap between the establishment survey (weak) and household survey (strong) is worth watching, these two measures rarely diverge this much, a possible sign of statistical noise worth confirming over coming months
CPI becomes the most important release on the upcoming calendar, it will determine whether this NFP was a one-off accident or the start of a genuine US labor market slowdown